Buying your first home is one of the biggest financial decisions you will ever make and in 2026, there is more support available to first time buyers than most people realise. Between government schemes, stamp duty relief, and dedicated savings accounts, the right combination of benefits can save you tens of thousands of pounds.
This guide covers every first time buyer benefit currently available in the UK, what each scheme offers, who qualifies, and how to combine them. And if you would rather talk it through with someone than research it alone, BM14 Finance is a specialist mortgage broker that helps first time buyers navigate exactly this process every day. Our office is located at 23 Bancroft Drive, Hempstead, Kent ME7 3TJ and Berkeley Square House, Mayfair, London W1J 6BD UK, so you can come and discuss everything. Our office hours are 11 am to 6 pm, Monday to Wednesday.
First Time Buyer Definition
Before you can claim any of the benefits below, it helps to know exactly what a first time buyer is. The official first time buyer definition used across UK mortgage lending, stamp duty relief, and the Lifetime Individual Savings Account (ISA) is:
“Someone who has never owned a residential property, anywhere in the world, either on their own or jointly with someone else.”
So who is classed as a first time buyer in practice? You will usually qualify if:
-
- You have never owned a home, freehold or leasehold anywhere in the world.
-
- You are buying the property as your only or main residence.
-
- You are purchasing with a mortgage (required for most scheme bonuses).
You are usually not classed as a first time buyer if you:
-
- Inherited a share of a property, even one you have never lived in.
-
- Previously owned a buy-to-let property, even if you have always rented yourself.
-
- Are buying jointly with someone who has owned a home before for stamp duty purposes, if either buyer has owned property before, neither of you qualifies as a first time buyer.
If you are not sure where you stand, it is worth checking with a mortgage advisor before applying for any scheme, getting this wrong can mean losing out on stamp duty relief or a LISA bonus you assumed you were entitled to.
Advantages of First-Time Buyer
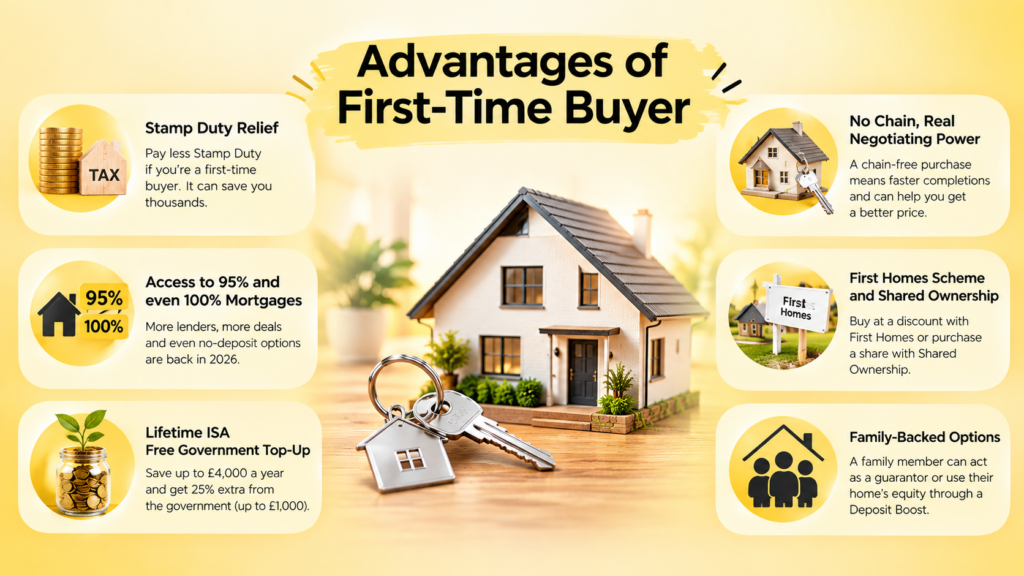
Being a first time buyer in the UK isn’t just a label, it comes with actual financial perks that home movers and landlords don’t get. From tax breaks to mortgage products designed specifically around your situation, understanding these first time buyer benefits will definitely shave thousands off your buying costs and open doors that would otherwise stay closed.
Stamp Duty relief
If you’ve never owned property before, you’re automatically eligible for reduced Stamp Duty Land Tax (SDLT). Since April 2025, the rates work like this:
|
Property price |
Stamp Duty owed |
|---|---|
|
Up to £300,000 |
£0 |
|
£300,001 – £500,000 |
5% on the portion above £300,000 |
|
Above £500,000 |
Relief lost — standard rates apply on full amount |
So on a £400,000 flat, you’d pay just £5,000 instead of the £12,000 a non-first-time buyer would owe. Worth checking this before you make an offer, because going even a few thousand pounds over £500,000 wipes out the relief entirely.
Access to 95% and even 100% mortgages
This is where things have genuinely changed in 2026. A few years ago, low-deposit lending nearly dried up. Now the market’s moved the other way: 537 different 95% LTV deals were available in February 2026, almost double what was on offer two years earlier, partly thanks to the government’s Mortgage Guarantee Scheme encouraging lenders back into this space.
And it’s gone further than that. Genuine no-deposit mortgages are back too:
- Skipton’s Track Record mortgage lets renters borrow up to 100% of a property’s value (up to £600,000) with no deposit at all, based purely on a clean 12 month rental payment history.
- Family Building Society relaunched its 100% LTV Family Mortgage in February 2026 for buyers with family backing.
- Lloyds and Accord both offer routes in with as little as a £5,000 deposit.
We’ve been fielding a lot more of these questions from first-time buyers at BM14 Finance this year, people who assumed they needed years of saving before they could even start looking. That’s not always true anymore, though rates on 100% deals do run higher, so it’s not automatically the cheapest route.
Lifetime ISA free government top-up
Save into a LISA and the government adds 25% on top, up to £1,000 a year, on savings of up to £4,000. Put in the maximum every year and that’s £5,000 in free money toward your deposit over time.
No chain, real negotiating power
Sellers love first-time buyers for one simple reason: there’s nothing to sell before you can complete. No chain means fewer things that can collapse a sale, faster completions, and honestly, it can even help you negotiate a slightly better price. Some sellers will take a lower offer from a chain-free buyer over a higher one that comes with risk attached.
First Homes Scheme and Shared Ownership
- First Homes Scheme: new-build properties at 30 to 50% below market value, though eligibility is stricter and often prioritises key workers and local buyers.
- Shared Ownership: buy between 10 to 75% of a home and pay rent on the rest, which lowers both your deposit and the mortgage you need to qualify for
Family-backed options
If saving alone feels impossible, a family member can act as guarantor or contribute through a Deposit Boost, using their own home’s equity to top up yours. It won’t put them on the property deeds, but it can be the difference between qualifying for a mortgage now versus waiting another two years.
That is where a UK mortgage broker (BM14 Finance) comes in. We are a UK based mortgages and insurance advisory firm regulated by the Financial Conduct Authority (FRN: 1040560), and our advisors work through every scheme against your income, deposit, and location to find the combination that actually applies to you. Explore our dedicated first-time buyer services, or get in touch to start the conversation.
Not sure which benefits you qualify for?
Talk it through with a BM14 Finance advisor and get a clear answer.
Government Schemes for First Time Buyers in 2026
The government runs several schemes to help first time buyers, and the line-up has changed in the last few years as older schemes closed and new ones took their place. Here is every scheme currently active across the UK.
Lifetime ISA (LISA): Save Smarter with a 25% Government Bonus
The Lifetime ISA is one of the strongest options for any first time buyer still in the saving stage. You can save up to £4,000 a year, and the government adds a 25% bonus on top, up to £1,000 free, every year.
To open a LISA you must be between 18 and 39. You can use the funds toward a first home costing £450,000 or less. Withdraw the money for any other reason before you turn 60 and you will face a 25% penalty, so it should stay earmarked for your home purchase.
If you are buying with another first time buyer who also holds a LISA, you can both use your own account on the same property, a couple could receive up to £2,000 in combined government bonuses every year they save.
See how much a LISA could add to your deposit
Run your numbers and see the 25% government bonus stack up over time.
Freedom to Buy (Mortgage Guarantee Scheme): Buy with Just a 5% Deposit
This is the permanent version of the Mortgage Guarantee Scheme, launched in July 2025 to replace the earlier temporary version. It helps you buy with just a 5% deposit by giving lenders a government guarantee on part of the loan.
You do not apply for this scheme directly, it works behind the scenes. When you approach a participating lender with a 5% deposit, the lender can offer a 95% mortgage knowing the government is backing part of the risk. Properties up to £600,000 are eligible, and it is open to both first time buyers and home movers.
Shared Ownership: Get on the Ladder with a Smaller Share
Shared Ownership lets you buy a percentage of a property 10% to 75% and pay rent on the rest to a housing association, buying more shares over time through a process called staircasing.
To be eligible, household income must be under £80,000 a year (£90,000 in London), and you must be a first time buyer or a previous homeowner who can no longer afford to buy outright. Bear in mind Shared Ownership properties are leasehold, so ground rent and service charges apply alongside your mortgage and rent.
First Homes Scheme: Buy a New Build at Up to 50% Off
The First Homes Scheme is the main government support for first time buyers in England now that Help to Buy has closed. Eligible buyers can purchase new-build homes at a minimum 30% discount, with some councils offering up to 50%.
To qualify, you must be a first time buyer over 18, buying in England, earning under £80,000 a year (£90,000 in London). The discount is permanent, when you sell, you must sell to another eligible first time buyer at the same percentage discount.
Do First Time Buyers Pay Stamp Duty?
Ah! 95% of clients ask, “Do first-time buyers pay stamp duty?” well most first time buyers in England and Northern Ireland pay no stamp duty at all but only up to a point. Stamp Duty Land Tax (SDLT) is one of the highest upfront costs of buying a home, and first time buyers get a significant reduction under rules that changed in April 2025 and still apply in 2026:
| Property Price | What You Pay (First Time Buyer) |
| Up to £300,000 | 0% — you pay nothing |
| £300,001 to £500,000 | 5% on the portion above £300,000 only |
| Over £500,000 | Standard rates apply — no first time buyer relief |
So a first time buyer purchasing a £350,000 home pays 5% on the £50,000 above £300,000 that is £2,500 in stamp duty, considerably less than without the relief. Before April 2025, the threshold was £425,000, so it is worth factoring stamp duty into your budget earlier than you might expect.
In Scotland, Land and Buildings Transaction Tax (LBTT) applies instead, with a 0% threshold of £175,000 for first time buyers. In Wales, Land Transaction Tax (LTT) applies under its own bands. Northern Ireland follows the same SDLT rules as England.
Work out your exact Stamp Duty before you offer
Know your true upfront cost in advance so your budget stays accurate.
First Time Buyer Savings Accounts: LISA vs Help to Buy ISA vs the New FTB ISA
The Help to Buy ISA closed to new accounts in November 2019. If you already hold one, you can still save up to £200 a month and claim a 25% bonus, though the cap is lower than the LISA’s. Here is how the current and proposed options compare:
| Feature | Lifetime ISA (LISA) | Help to Buy ISA (existing only) | FTB ISA (proposed) |
| Annual Limit | £4,000 | £200/month (£2,400/yr) | Not yet confirmed |
| Government Bonus | 25% (up to £1,000/yr) | 25% (£3,000 lifetime cap) | Not yet confirmed |
| Max Property Price | £450,000 | £250,000 (£450k in London) | Not yet confirmed |
| Age to Open | 18–39 | 18–39 | 18+, no upper limit (proposed) |
| Early Withdrawal Penalty | 25% | None (just no bonus) | None (proposed) |
For now, the LISA remains the strongest option for most first time buyers starting fresh, higher annual limit, higher bonus, and a more expensive property ceiling than the closed Help to Buy ISA.
Mortgage Help for First Time Buyers
What Is the Mortgage Guarantee Scheme?
Now permanent and known as Freedom to Buy, the Mortgage Guarantee Scheme encourages lenders to offer high loan-to-value mortgages. It does not hand you money directly, it acts as a safety net for lenders, reducing the risk of lending to someone with a small deposit, which is why more lenders are now willing to offer 95% mortgages than would otherwise be the case.
Can I Get a Mortgage with a 5% Deposit?
Yes, the Freedom to Buy scheme makes this possible with participating lenders across the UK. You will still need to pass affordability checks and have a reasonable credit history, and 95% mortgages tend to carry higher interest rates than lower LTV deals. If you can stretch to a 10% deposit instead, you will usually get a meaningfully better rate.
How Much Can I Borrow as a First Time Buyer?
Most lenders offer between 4 and 4.5 times your annual income as a maximum loan, so someone earning £35,000 could typically borrow between £140,000 and £157,500. If you are buying jointly, lenders usually combine both applicants’ income, though some lenders offer higher multiples for certain professions or higher earners.
Nationwide mortgage rates for first time buyers vary a lot from lender to lender, and they move constantly, so what looks like the best deal this month can change by the next. Rates depend on your deposit size, credit history, income, and how long you fix for, which is why comparing offers across the whole market rather than settling for the first rate you’re quoted usually makes a real difference to your monthly repayments. Comparing options like this across the market is exactly the kind of work a specialist mortgage broker like BM14 Finance handles for you, matching you to lenders most likely to approve your application at the best available rate. Once you know your budget, our mortgage application process walks you through exactly what happens next, step by step.
Curious what YOU could actually borrow?
Income multiples are just a start, your real borrowing power depends on more.
Which First Time Buyer Scheme is Right for Me?
There is no single scheme that works for everyone, it depends on your situation. Here is a simple way to think about it:
| Your Situation | Most Relevant Scheme |
| Still saving, aged 18–39 | Lifetime ISA |
| Ready to buy, only have a 5% deposit | Freedom to Buy (Mortgage Guarantee Scheme) |
| Cannot afford full ownership | Shared Ownership |
| Buying a new-build in England | First Homes Scheme |
| Council tenant for 3+ years | Right to Buy |
| Buying a new-build in Wales | Help to Buy Wales (closes Sept 2026) |
| Buying in Scotland, low-to-moderate income | LIFT (New Supply Shared Equity) |
| Buying in Northern Ireland | Co-Ownership Scheme |
| Building your own home | Help to Build |
Many buyers combine schemes, for example, using a LISA to build a deposit, then Freedom to Buy for a 95% mortgage. Talking to a qualified mortgage advisor is the most reliable way to work out which combination suits your income, savings, and location.
First Time Buyer Benefits: England vs Scotland vs Wales vs Northern Ireland
Benefits are not identical across the UK, each nation runs its own property tax system and its own version of some schemes:
| Benefit | England | Scotland | Wales | Northern Ireland |
| Stamp Duty Relief | 0% up to £300,000 | LBTT 0% up to £175,000 | LTT — different bands | Same as England (SDLT) |
| Equity Loan Scheme | Closed (2023) | Not available | Open until Sept 2026 | Not available |
| Shared Ownership | Available | LIFT (shared equity) | Available | Co-Ownership scheme |
| First Homes Scheme | Available | Not available | Not available | Not available |
| Right to Buy | Available | Abolished | Available (limited) | Separate scheme |
Biggest First Time Buyer Mistakes to Avoid
Knowing the schemes exist is only half the battle, many first time buyers lose money or delay their purchase through avoidable mistakes:
-
- Waiting too long to open a Lifetime ISA: the bonus is capped per tax year, so starting late means missing out on free money.
-
- Misunderstanding the LISA withdrawal penalty: the 25% charge takes more than just the bonus back, leaving you with less than you paid in if withdrawn for the wrong reason
-
- Assuming every property qualifies: First Homes, for example, only applies to certain new-build properties designated by local councils
-
- Underestimating Shared Ownership costs — you pay a mortgage on your share, rent on the rest, and service charges, and some buyers do not budget for all three
-
- Going straight to your own bank instead of using a mortgage broker, who has access to far more lenders and knows which ones are likely to approve your application
-
- Skipping the mortgage in principle: locking one in before you have an accepted offer shows sellers you are serious and often speeds up the process
For more on avoiding costly missteps once you are house-hunting, read our guide to negotiation first time buyer tips.
Ready to start your first-time buyer journey?
A short conversation with BM14 Finance can save you thousands, and a lot of stress.
Frequently Asked Questions
What are the advantages of being a first time buyer?
First time buyers get access to benefits ordinary movers do not: stamp duty relief on the first £300,000 of a property, a 25% government bonus through the Lifetime ISA, 5% deposit mortgages via Freedom to Buy, discounted new-builds through the First Homes Scheme, and Shared Ownership options that lower the deposit and income needed to get on the property ladder.
What is a first time buyer?
A first time buyer is someone who has never owned a residential property anywhere in the world, either alone or jointly with someone else, and who is buying a home as their only or main residence.
What is the first time buyer definition in the UK?
The standard first time buyer definition used for UK stamp duty relief, the Lifetime ISA, and most government schemes is a person who has never owned an interest in a residential property, in the UK or abroad.
Who is classed as a first time buyer?
You are generally classed as a first time buyer if you have never owned any share of a home, whether inherited, gifted, or purchased, and you are buying your first property as your main residence with a mortgage. If you are buying jointly, both applicants usually need to meet this criteria for the couple to qualify for first time buyer relief.
Can I get a £200,000 mortgage on a £40,000 salary?
There is no single yes-or-no answer, since it depends on your deposit, credit history, existing debts, and each lender’s own affordability criteria, most lenders offer 4 to 4.5 times income as a starting point, which on a £40,000 salary points to roughly £160,000–£180,000 before other factors are weighed in. The first step is to discuss your situation directly with BM14 Finance, we take the time to understand your circumstances and requirements, and then work through the suitable mortgage options actually available to you, rather than relying on a generic multiple that may not reflect what a real lender would offer.
How much do first-time homebuyers get from the government?
There is no direct cash handout, support comes through savings and discounts instead. A Lifetime ISA can add up to £1,000 a year in bonuses, stamp duty relief can save several thousand pounds on the purchase itself, and the First Homes Scheme can knock 30–50% off a new-build price. Combined, these benefits regularly add up to tens of thousands of pounds depending on the property and scheme mix used.
What are the biggest first-time home buyer mistakes?
The most common mistakes are opening a Lifetime ISA too late, misunderstanding the LISA withdrawal penalty, assuming a property qualifies for a scheme without checking, underestimating the combined costs of Shared Ownership, going straight to your own bank instead of a broker, and skipping the mortgage in principle before house-hunting.
Do first time buyers pay stamp duty?
Only above a threshold. In England and Northern Ireland, first time buyers pay no stamp duty on the first £300,000 of a property, then 5% on the portion between £300,001 and £500,000. Above £500,000, standard rates apply with no first time buyer relief. Scotland and Wales use their own separate property tax systems and thresholds.