If you’re searching for houses for sale for first time buyers in London, you’ve probably already noticed the numbers don’t quite add up on their own. The average price paid by a first-time buyer in the capital was £472,000 in April 2026 (Land Registry), more than double the England-wide average of £228,000. That’s the reality but it’s not the whole story, because there are still real, working routes onto the property ladder in London if you know where to look.
This guide runs through the current government schemes, who actually qualifies, and where to go next.
Before You Browse Listings: What to Check First
Before you start scrolling property listings, there’s one step that saves most first-time buyers weeks of wasted viewings: knowing your real budget and which schemes you actually qualify for. Online listing sites will show you thousands of results, but without a confirmed budget or an Agreement in Principle, you won’t know which of those are genuinely within reach, or whether a scheme like First Homes or Shared Ownership changes what you can afford.
This is exactly where BM14 Finance comes in first, not after you’ve found a place. We check your income, deposit and eligibility, get you an Agreement in Principle so agents and developers take you seriously, and tell you which price bracket and boroughs actually make sense for your situation. For First Homes specifically, availability depends on what’s being built in your borough at any given time, so we also flag active or upcoming developments where relevant when we’re working with you.
Once that’s sorted, browsing listings becomes a lot more focused, you’re only looking at homes you can actually secure. Get your budget confirmed first
Are You Searching New Houses for Sale Near Me?
If you’re searching by postcode for what’s new and available near you, it’s worth knowing a few things before you get attached to a development, most listing sites won’t tell you these upfront.
New builds usually carry a 10-year NHBC (or equivalent) warranty, but you should still arrange a snagging inspection before completion, minor defects are common and easier to get fixed pre-completion than after you’ve moved in. Check the service charge and any ground rent too, new-build flats especially can carry ongoing costs that don’t show up in the headline price.
On the mortgage side, new builds have their own timing pressure. Developers often want exchange within a set window (commonly 28 days), and your mortgage offer needs to stay valid all the way to completion, which can be months away on an off-plan purchase. Not every lender handles this the same way, and some are noticeably slower or stricter on new-build valuations. Certain new builds also qualify for schemes like First Homes or Own New, Rate Reducer, covered above, which can meaningfully cut your monthly payments.
BM14 Finance works with lenders who are comfortable with new-build exchange deadlines and off-plan timelines. If you’ve found a development near you, get in touch before you pay a reservation fee, we’ll confirm what you can actually secure and flag anything in the small print that could cost you later
As a UK Based Mortgage Broker, Here’s How BM14 Finance Helps Our Clients
Reading through scheme criteria is one thing, working out which one actually fits your income, deposit, and the part of London you want to buy in is another. That’s genuinely where most first-time buyers get stuck, and it’s the part we spend most of our time on with clients.
At BM14 Finance, we work across the complete mortgage application process for first-time buyers, from checking your eligibility for schemes like First Homes and the Mortgage Guarantee Scheme, to comparing nationwide mortgage rates across mainstream lenders (Barclays, HSBC, Nationwide, Halifax) and 190+ specialist lenders who take a more flexible view on affordability. In our experience advising London-based buyers, the biggest difference usually isn’t the scheme you pick, it’s getting the right lender for your specific income and deposit situation, since criteria vary a lot more than most buyers expect.
We’ve also seen several clients get caught out by the £500,000 stamp duty relief cutoff simply because nobody flagged it early in the process, it’s exactly the kind of detail we check before you get attached to a property, not after.
We look at your complete documents like income, deposit, credit history, and which government scheme (if any) suits you and help you find the best mortgage deal for first time buyers in your circumstances, without pushing you toward one lender over another. If you’re weighing up first time buyer benefits like First Homes against Shared Ownership or a standard 95% mortgage, it’s worth having that conversation before you start viewing properties, not after you’ve found “the one.”
We have suitable options available depending on your situation, so it’s worth a proper discussion rather than guessing from a scheme comparison page. Whether you’re buying in London or over in Hempstead, Kent, we work with clients across both areas. Get in touch with our office and we can talk through what actually applies to you.
Our office Hours: 11 am to 6 pm, Monday to Wednesday.
Discuss with BM14 Finance
Not sure which scheme actually fits your situation?
Discuss your situation with us and we will give you the best available options for you.
First-Time Home Buyer Government Grant
There isn’t a single cash “grant” for first-time buyers in the UK anymore, that’s a common misconception, and one we hear from clients fairly often. What exists instead is a mix of government-backed schemes: price discounts, deposit guarantees, and savings top-ups.
Do First Time Buyers Pay Stamp Duty? Yes, but with relief. First-time buyers pay 0% stamp duty on the first £300,000 of a property, and 5% on the portion between £300,001 and £500,000. The catch for London buyers: this relief only applies to homes priced at £500,000 or under and with the median London property well above that, plenty of first-time buyers here end up paying standard stamp duty rates with no relief at all.
First-Time Buyer Government Scheme in 2026
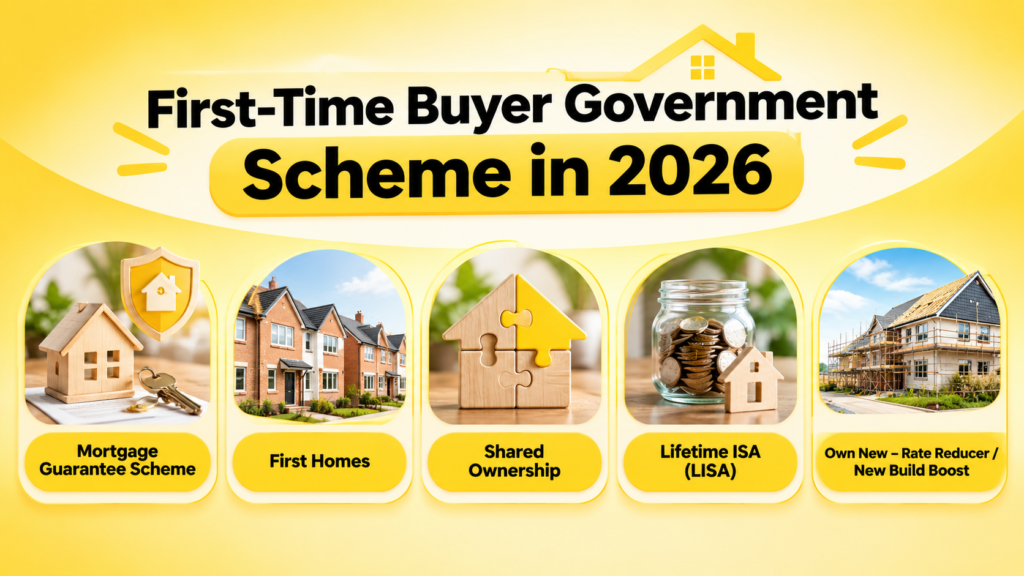
Here’s where things stand in 2026:
-
- Mortgage Guarantee Scheme (now called “Freedom to Buy”) made permanent from July 2025. It lets you buy with just a 5% deposit, with the government guaranteeing part of the loan to the lender. Property price cap: £600,000.
-
- First Homes — new-build homes sold at a 30-50% discount to market value, permanently.
-
- Shared Ownership — buy a share (usually 10-75%) of a home and pay rent on the rest.
-
- Lifetime ISA (LISA) — a 25% government top-up on savings, though this is being phased out. A new First-Time Buyer ISA is expected around August 2027, with no age limit and no withdrawal penalty.
-
- Own New – Rate Reducer / New Build Boost — developer-backed schemes offering reduced mortgage rates or interest-free equity loans on new builds.
Each of these tackles a different bottleneck, a small deposit, a high price, or a high mortgage rate, so it’s worth pinning down which one is actually holding you back before you pick a scheme to chase.
Free tool
Know your budget in a few seconds
The First Homes Scheme
First Homes is currently one of the most talked-about options for London buyers, and for good reason.
It offers newly built homes at a discount of 30% to 50% below market value and that discount is passed on every time the home is resold, so it stays affordable long-term, not just for the first buyer.
-
- Maximum price after discount: £420,000 in London (£250,000 elsewhere in England).
-
- You’ll need a mortgage covering at least 50% of the discounted price.
-
- Councils can add local priority rules (key workers, local connection) for the first 3 months a home is listed.
The main drawback in London specifically: availability is patchy, and there’s no single national portal listing every First Homes property, you often have to check with individual developers or local estate agents directly.
More First-Time Buyer Schemes
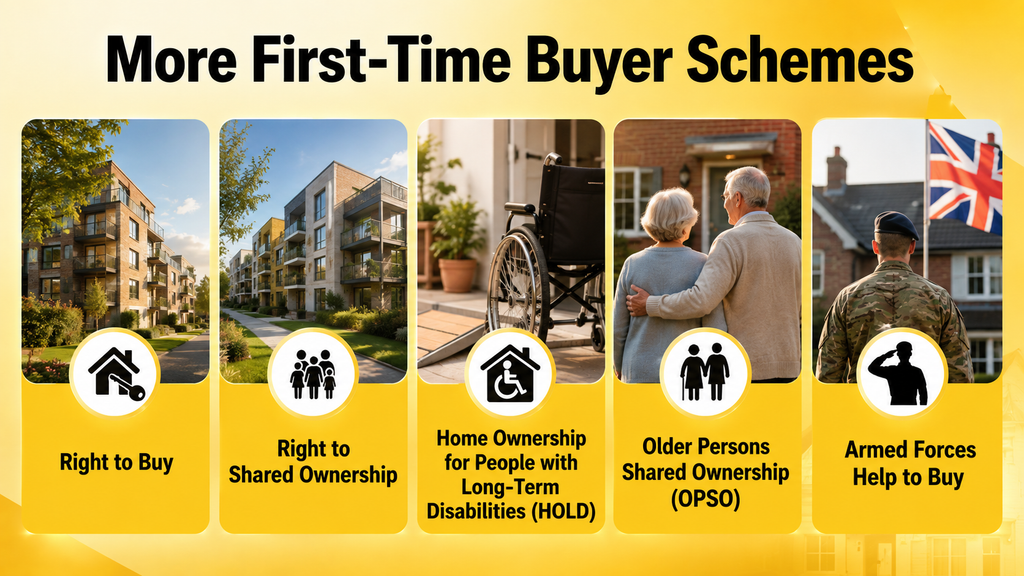
First Homes and Shared Ownership get most of the attention, but they’re not the only options. It could be worth checking out:
Right to Buy: If you’re a council tenant, you could get a discount of up to £16,000 in most of London (a small number of boroughs, including Barking and Dagenham, allow up to £38,000), based on your property type and how long you’ve been a tenant.
Right to Shared Ownership: For social or affordable housing tenants in England who’ve been in their home for at least 3 years. You can buy a share of between 10% and 75%.
Home Ownership for People with Long-Term Disabilities (HOLD): Helps people with a long-term disability buy a home on the open market through a shared ownership arrangement, where an equivalent standard shared ownership property isn’t suitable.
Older Persons Shared Ownership (OPSO): For buyers aged 55 and over, letting you buy a share of 10% to 75% in a home designed for later living.
Armed Forces Help to Buy: Serving armed forces personnel can access an interest-free loan of up to 50% of their salary, capped at £25,000, repayable interest-free over 10 years.
190+ lenders compared
From mainstream banks to specialist lenders, we’ll match you to the one that actually fits your circumstances.
Who is Eligible for the First Homes Scheme?
Eligibility Criteria
To qualify for First Homes, you’ll generally need to meet all of the following:
-
- Be a genuine first-time buyer (never owned a home in the UK or abroad).
-
- Be 18 or older.
-
- Have a combined household income of no more than £90,000 a year in London (£80,000 elsewhere).
-
- Be able to secure a mortgage for at least 50% of the discounted purchase price.
-
- Buy a home that will be your only or main residence.
Terms and Conditions
A few conditions worth knowing before you get attached to a property:
-
- The discount is fixed as a percentage and applies forever, even when you sell.
-
- You can generally only sell to another First Homes-eligible buyer.
-
- Letting out the property usually needs approval from your local authority and mortgage lender.
-
- Local eligibility rules (key worker priority, local connection) only apply for the first 3 months a home is on the market.
FAQs
Is now a good time to buy a house in the UK?
It depends on your own readiness rather than the market alone. That said, buyer conditions have eased somewhat in 2026, housing stock is at its highest level since 2015, and homes in London are taking longer to sell than a year ago, giving buyers more room to negotiate. Mortgage rates remain a bigger factor than timing the market.
Can you buy a house from a housing association?
Yes, in most cases. Housing association tenants have two main routes: Right to Acquire, which offers a fixed discount similar in spirit to council Right to Buy, or staircasing to full ownership if you’re already in a Shared Ownership property. Which route applies depends on how your tenancy started and how the home was funded.
Can I buy my housing association house?
It depends on the specific property and your tenancy history rather than a blanket yes or no. Eligibility for Right to Acquire generally requires the home to have been built or bought with public subsidy after April 1997, and you’ll usually need a minimum tenancy period behind you. The fastest way to check is to ask your housing association directly for your property’s eligibility status, since not every home in their portfolio qualifies.
Can I buy my house from the housing association?
If it’s eligible, the process runs through your landlord rather than the open market, you formally apply for Right to Acquire, they confirm eligibility and set the discounted price, and you then arrange your mortgage against that figure. The discount here is a fixed cash amount rather than the percentage-based discount used in council Right to Buy, so it’s worth getting the exact figure from your landlord before assuming what you’ll save.
Can you buy council houses?
Yes, through the Right to Buy scheme, if you’re a secure council tenant. Discounts in London currently range from £16,000 up to £38,000 in select boroughs, depending on property type and tenancy length. If you go ahead, BM14 Finance can help you arrange the mortgage against the discounted price.